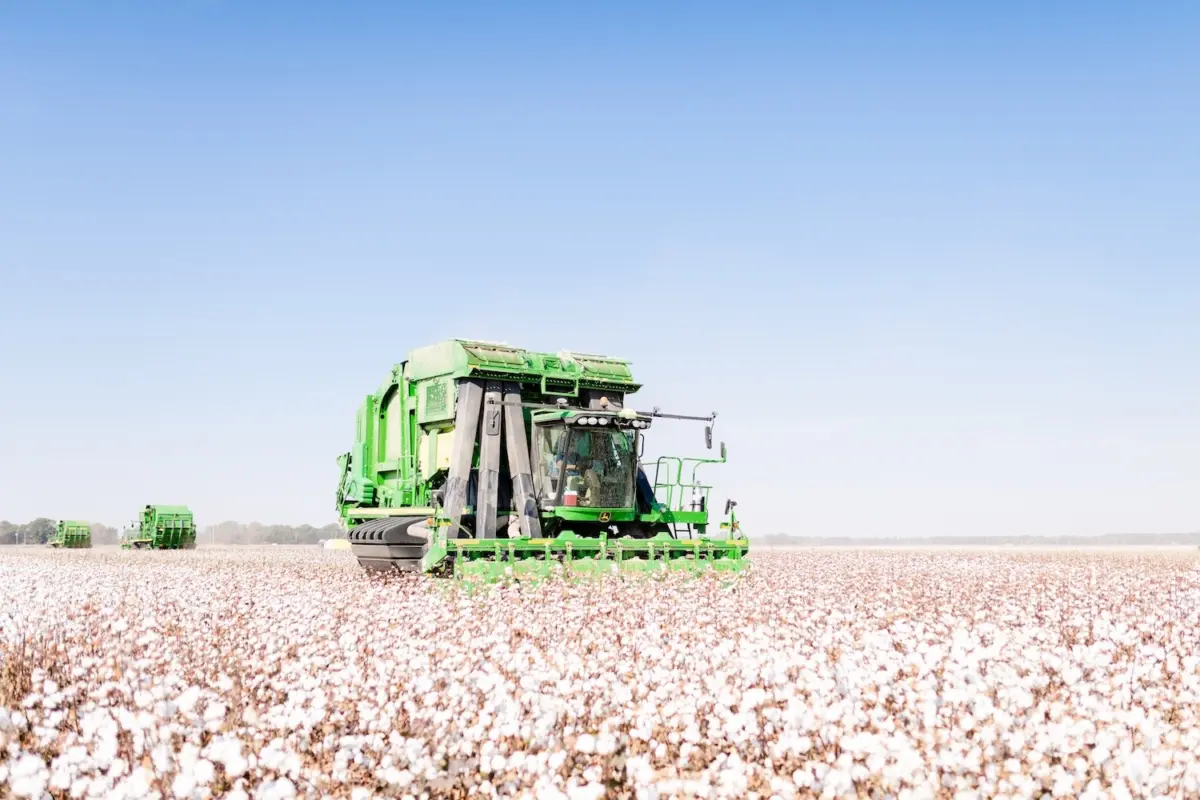
It is an old and well-established adage that U.S. farmers feed the world. Yet, as the global agricultural and industrial landscape continues to evolve, a strong parallel argument can be made: American growers help clothe the world as well. The United States consistently ranks among the top cotton-producing nations globally, and American agriculturalists have firmly established themselves as leaders in responsible agriculture and land stewardship.
As the modern apparel industry increasingly grapples with mounting concerns over waste, pollution, and the environmental footprint of textiles, makers of everything from sportswear, activewear, denim, T-shirts, and everyday athleisure apparel might well consider the eco-conscious and sustainable option that U.S. cotton naturally presents.
Recent data and lifecycle assessments highlight the measurable progress made by U.S. cotton growers over recent decades, offering brands and retailers a science-backed natural fiber choice that aligns closely with shifting consumer demands and regulatory pressures.
Jesse Daystar, Ph.D., vice president and chief sustainability officer at Cotton Incorporated, detailed the significant and quantifiable strides achieved by domestic cotton producers during an interview discussing findings from the organization’s research initiatives.
“Over the past four decades, U.S. cotton has reduced soil loss by 45 percent, improved irrigation water-use efficiency by 58 percent, reduced greenhouse gas emissions by 25 percent and improved land-use efficiency by 30 percent,” Daystar told the Lifestyle Monitor, referencing data drawn from Cotton Incorporated’s 2023 National Resource Survey.
“That progress is tied to better practices and better tools. More growers are using cover crops, reduced tillage, no-till or strip-till, precision agriculture, irrigation scheduling, flow meters and soil moisture monitoring.”
Further reinforcing these on-farm advancements, Cotton Incorporated commissioned WSP USA Inc. to conduct a comprehensive, data-driven life cycle assessment (LCA) examining U.S. cotton fiber production from the field to the gin. The assessment revealed that cotton’s natural fiber composition inherently creates biogenic carbon dioxide storage—a crucial physical distinction that separates it from petroleum-based synthetic fibers.
When temporary biogenic carbon dioxide flows are accounted for, the LCA demonstrated that cotton production achieves a net negative cradle-to-gate emission rate of -0.264 kilograms of CO2 per kilogram of U.S. cotton fiber. Furthermore, the assessment identified clear opportunities to enhance cotton circularity and bolster the permanence of this carbon storage, solidifying U.S. cotton’s standing as a credible, scientifically verified natural fiber alternative for brands, retailers, and consumers alike.

The timing of these environmental findings intersects with a pronounced shift in consumer consciousness regarding sustainability. According to the 2025 Global Lifestyle Monitor Survey—conducted by Cotton Council International and Cotton Incorporated across 13,026 respondents—three out of four consumers, or 75 percent, express a strong interest in sustainable clothing. For these shoppers, sustainability is viewed as either an essential purchase criterion, cited by 21 percent, or a highly desirable attribute, noted by 54 percent.
The survey further highlights a stark contrast in how consumers perceive different fiber types. Fully 83 percent of respondents view cotton and other natural fibers as safe for the environment. In contrast, fewer than half of consumers share that level of environmental confidence when evaluating manmade fibers, including rayon at 48 percent, polyester at 46 percent, and Tencel at 41 percent.
Daystar noted that the 2023 Natural Resource Survey demonstrates a steady, continued adoption of conservation-oriented farming practices across the agricultural sector. The utilization of cover crops expanded significantly, increasing from 20 percent of survey respondents in 2015 to 48 percent in 2023. Similarly, the implementation of no-till and strip-till methods grew steadily between 2008 and 2023, while conventional tillage practices saw a corresponding decline.
This widespread dedication to improving on-farm sustainability does not go unnoticed by the end consumer. Brands and manufacturers evaluating market preferences should take note that 75 percent of shoppers explicitly favor apparel crafted from cotton, cotton blends, or denim. These three categories enjoy an overwhelming preference among consumers when compared against synthetic alternatives such as polyester at 7 percent, spandex at 5 percent, and rayon at 4 percent.
Despite strong consumer preference for natural fibers, apparel brands frequently cite the lower initial cost of polyester as a primary driver for its ubiquitous use in garment manufacturing. Meanwhile, the broader fashion industry faces intense scrutiny for generating extraordinary levels of textile waste stemming from overproduction and large volumes of unsold garments.
Data from the United States Environmental Protection Agency highlights the severity of this domestic waste crisis, revealing that in America alone, 85 percent of all discarded textiles end up in landfills on an annual basis.
This waste issue is compounded by the material composition of modern clothing. Nearly 70 percent of the world’s textile fibers are now synthetic, with petroleum-based polyester dominating the market. Whether through everyday wear or routine laundering, all garments shed microscopic fibers during their lifecycle. However, the fibers released from synthetic, petroleum-based fabrics are classified as microplastics. These materials can take hundreds of years to degrade fully, releasing microplastics into the air, water systems, and soil, thereby exacerbating the escalating global challenge of microplastic pollution.
“There’s a gap between how the fashion industry talks about responsible, regenerative agriculture and what’s actually been happening on U.S. cotton farms for years,” said Liz Hershfield, executive director of Cotton USA and co-director of the U.S. Cotton Trust Protocol, during an interview with the Lifestyle Monitor. Responsible cotton stewardship is a foundational principle that growers have built their businesses around, she emphasized, noting that without it, the viability of the agricultural sector is compromised.

Hershfield highlighted that cotton growers were among the earliest agricultural adopters of advanced precision farming tools. These technologies include satellite imagery, sophisticated drone deployment, and artificial intelligence-driven agronomic management systems that allow producers to optimize crop yields while simultaneously minimizing their environmental impact.
The economic and ecological arguments for natural fibers are further reinforced by global consumer sentiment. Around the world, the majority of consumers—approximately 59 percent—report that they are willing to pay a higher price for clothing manufactured from natural fibers like cotton, according to findings from the 2025 Global Lifestyle Monitor research. This willingness to pay a premium is even more pronounced in specific international markets, reaching 85 percent in India and 66 percent in Mexico.
Furthermore, consumers consistently rank cotton as their preferred material because they perceive it as the most comfortable, cited by 67 percent of respondents; the softest, noted by 66 percent; the highest quality, reported by 59 percent; the most sustainable, indicated by 49 percent; and the longest-lasting, cited by 44 percent.
“Apparel brands should care because the sustainability story of a garment starts with the fiber,” Daystar said. “U.S. cotton gives brands a natural, trusted and data-backed fiber with a real story of continuous improvement from the farm forward.”
Hershfield warned that apparel brands often fail to realize the broader socio-economic stakes involved when corporate sourcing decisions consistently favor fossil fuel-based synthetics over renewable natural fibers like cotton.
There are more than 15,000 active cotton farms distributed across 17 states, and 98 percent of those agricultural operations are family-owned and family-operated, according to industry data. The long-term economic futures of these farming families are shaped, in part, by the purchasing and sourcing decisions made by major fashion brands.
Growers have been forced to absorb difficult and volatile market conditions for several years. Agricultural infrastructure that has been built and refined over generations can quickly erode when market demand fails to provide adequate support. That reality, Hershfield noted, represents an area where fashion brands hold significantly more influence than they often realize.