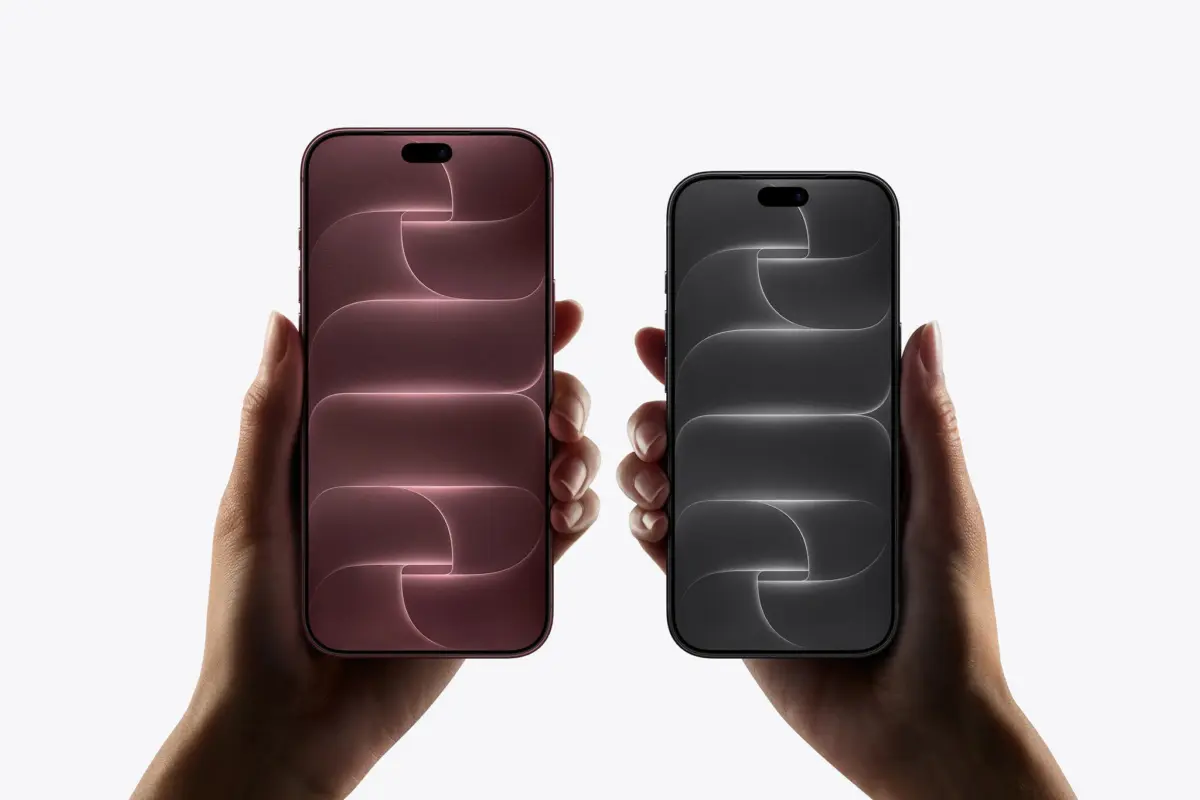
As Apple introduces its latest generation of smartphones, consumers are greeted not only by advanced new hardware features and innovative form factors, but also by a noticeable bump in price tags across the board. The flagship iPhone 18 Pro now commands a starting price of $1,200, representing a $100 increase over the base-model iPhone 17 Pro from the previous year. Similarly, the larger iPhone 18 Pro Max enters the market at a starting price of $1,300, marking its own $100 upward shift compared to its predecessor.
Beyond the traditional slab phones, Apple is also preparing for the October market introduction of the highly anticipated iPhone Duo, a folding phone priced at $2,000. However, for most consumers looking to acquire these premium devices without paying the full lump sum upfront, a variety of financing and leasing structures are readily available to break the cost down into smaller, more manageable payments.
This upward pressure on pricing is not isolated to Apple’s product ecosystem. Across the broader technology landscape, research firm IDC projects that the average selling price of mobile phones globally will jump by 30% year over year. This widespread inflation is driven in part by escalating memory costs, a component shortage and pricing squeeze that has simultaneously triggered skyrocketing prices for laptops and other personal computing devices.
Faced with these higher entry barriers, shoppers increasingly rely on installment plans and lease agreements to absorb the blow. According to Nabila Popal, senior research director at IDC, these payment mechanisms allow consumers to justify purchasing higher-tier devices by shifting their focus away from the total retail cost and toward the monthly financial obligation. At the end of the day, Popal notes, even with sophisticated financing tools at their disposal, the primary question most consumers ask is simply what their monthly payment will be.
Decoding the Numbers: Buying Versus Leasing Directly From Apple
When purchasing a new smartphone directly through Apple, consumers generally choose between three distinct financial pathways: buying the device outright at full retail price, entering a traditional financing agreement with monthly installments, or leasing the hardware through the Apple Upgrade program.
Traditional financing is structured for individuals with a solid credit history, enabling them to spread the total cost of the phone over a 24-month period with zero percent APR. In certain cases, shoppers can extend these payments out to 36 months, though this extended timeline requires committing to specific major wireless carriers—namely AT&T, T-Mobile, or Verizon—at the exact moment of purchase. Once the final month of the financing term is reached, whether at 24 or 36 months, the device is fully paid off, and ownership transfers completely to the consumer.
The Apple Upgrade program operates under a fundamentally different model by treating the transaction as a lease rather than a traditional purchase. Because participants are leasing the phone rather than paying off its complete retail value over time, the monthly payments are lower than those associated with standard financing. These lower monthly rates are available across 12- or 18- to 24-month terms, and the lease structure extends beyond iPhones to encompass other ecosystem hardware, including newly announced Apple Watch models, iPads, and Mac computers.
To illustrate the financial breakdown using the iPhone 18 Pro, an outright purchase or standard 24-month financing plan requires monthly payments of $49.95, after which the customer owns the device outright. Choosing to lease the exact same phone through the Apple Upgrade program reduces the monthly obligation to $34.99, since the consumer is not paying down the device’s residual value. Applying an eligible device trade-in can reduce that monthly cost even further.
At the conclusion of an Apple Upgrade lease term, participants face a pivotal choice. They can choose to upgrade to the newest iPhone generation, which seamlessly continues their monthly payment cycle under a new agreement, or they can return the hardware to Apple to terminate the contract entirely. For consumers who decide they want to keep their current phone rather than trade it up or return it, they must pay Apple the remaining balance. For an iPhone 18 Pro, keeping the device means paying an additional lump sum of $359 on top of the roughly $840 paid out across the 24-month lease.
Industry analysts hold differing views on the merits of these leasing structures. Avi Greengart, president of the consumer technology analysis firm Techsponential, views the Apple Upgrade program as a favorable deal for shoppers because it operates without hidden fees, carrying the same total cost over two years as an outright cash purchase.
Conversely, consumer advocate Clark Howard cautions that leasing programs can subtly incentivize consumers into an ongoing cycle of continuous debt as newer models perpetually replace older ones. The danger, according to Howard, is that consumers enter a perpetual lease where they are forever locked into a recurring monthly bill, creating what he describes as a financial bear trap.
The Role of Wireless Carriers and Multi-Year Contracts
Wireless carriers offer their own competitive installment plans for purchasing new hardware, operating on principles similar to manufacturer financing. As Popal explains, carrier financing grants the consumer eventual ownership of the device, but requires payments spread across a predetermined number of months.
In recent years, major carriers have increasingly leaned toward 36-month installment agreements. By stretching the payment window across three full years, carriers can present significantly lower monthly payments to consumers compared to what they would encounter on a standard 24-month plan. However, this cost reduction comes with a significant trade-off, binding the customer to that specific carrier for the entire duration of the financing contract.
Interestingly, the baseline monthly financing costs across major national carriers remain nearly identical. Financing plans from AT&T, T-Mobile, and Verizon all require 36 monthly payments of $33.34 for the iPhone 18 Pro, with Verizon pricing its equivalent plan a single penny lower than its competitors.
Instead of differentiating on the base installment price, carriers compete heavily through promotional deals and trade-in rebates tied to the new device launches. AT&T and T-Mobile both offer up to $1,200 in bill credits when customers trade in an eligible device and enroll in specific unlimited data plans. Meanwhile, Verizon provides an alternative path via a $50-per-month financing program that includes an annual upgrade benefit, allowing customers to transition to a new phone every year.
Evaluating Long-Term Financial Commitments
Choosing between leasing and financing a smartphone ultimately hinges on individual financial priorities, including desired monthly budget thresholds, the preferred duration of payment commitments, and long-term upgrade habits. While leasing through Apple provides the flexibility of shorter 12- or 24-month terms and lower monthly outlays, traditional financing ensures that the consumer holds full ownership of the hardware once the term concludes. Leases require a residual balloon payment if the user decides against upgrading and opts to keep the device.
Furthermore, Apple’s leasing program is engineered to facilitate effortless upgrades, bypassing the restrictions typically imposed by traditional financing plans that prevent customers from upgrading until their current phone is completely paid off. There are occasional exceptions among carriers, such as T-Mobile’s Flex 36 offering, which includes an early-upgrade provision allowing customers on eligible data plans to acquire a new device once they have paid off more than half of their current hardware balance.
For consumers who prioritize having the latest technology in their hands year-round, industry critics like Howard concede that programs such as Apple Upgrade serve a practical purpose. Yet, analysts warn that the psychological comfort of manageable monthly installments can easily obscure broader financial realities. As Greengart emphasizes, the primary pitfall to watch out for is purchasing more technology than one actually needs, reminding shoppers that favorable lease terms make large purchases digestible on a monthly basis, but do not automatically mean the device fits comfortably into a sound overall financial plan.