

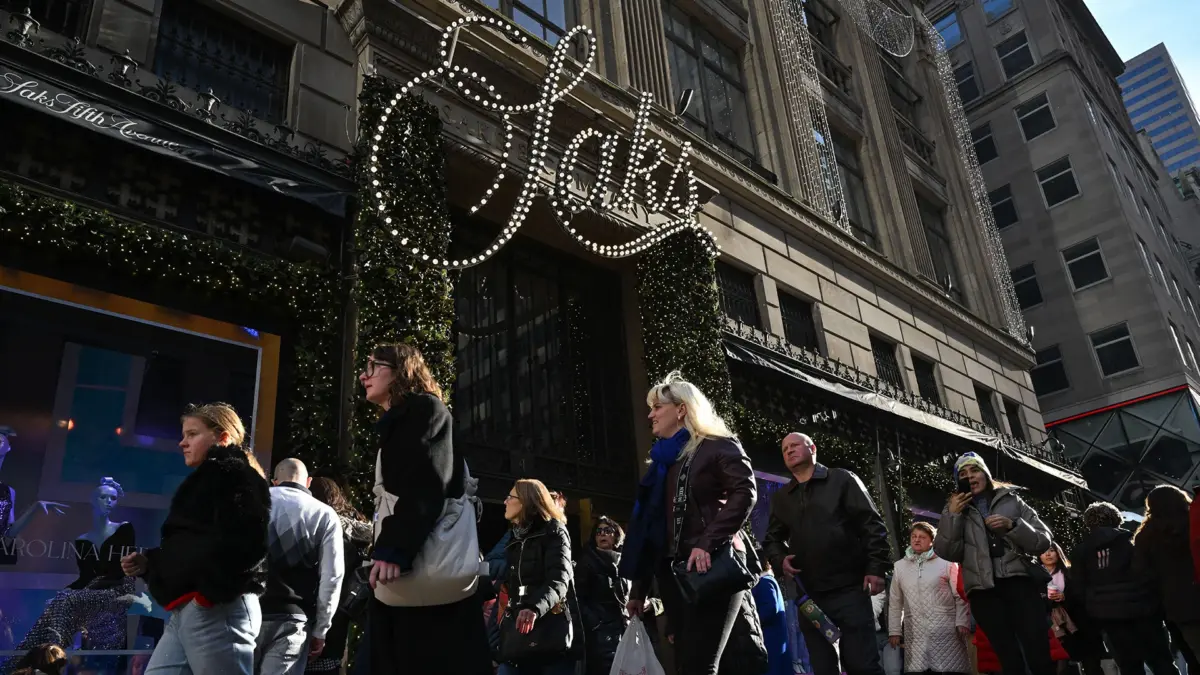
Long before shopping was dictated by online algorithms and targeted digital ads, it had Saks Fifth Avenue. For generations of luxury buyers, the name alone was synonymous with elegance, glamour, and impeccably curated taste. Inside its Midtown Manhattan flagship, fashion designer Donatella Versace once declared, “Saks is New York,” yet its influence extended far beyond the boundaries of Manhattan. Its sumptuous, sprawling stores across the country became coveted lifestyle destinations in their own right, defining the pinnacle of American department store culture.
From Armani to Zegna, Saks carried rack upon rack of enticing indulgences. Shoppers could find Oscar de la Renta evening gowns alongside snakeskin Gucci loafers, Montblanc fountain pens next to Dior eaux de toilettes, and precisely tailored Ralph Lauren suits paired with matching Burberry trench coats for both adults and children. There were Chanel 2.55 handbags and Louis Vuitton briefcases, alongside the retailer’s own house-label offerings, which included beautifully crafted pearl necklaces, buttery calfskin gloves, and extra-soft cashmere pullovers and cardigans.
“Saks was the reliable destination where you knew you could find whatever you wanted,” says Julia Stedman, a New York–based brand-strategy consultant who works across fashion and technology and shopped at the retailer for decades. “Every luxury brand was there.”
Footwear was a particularly powerful draw, anchored by elite labels such as Manolo Blahnik, Roger Vivier, Jimmy Choo, and Christian Louboutin. At the imposing Manhattan flagship—a Midtown magnet for locals and tourists alike since it first opened its doors in 1924—the massive eighth-floor designer-shoe department earned a distinct cultural milestone that no other retail space in the country could claim. In August 2007, the United States Postal Service granted the floor its very own zip code: 10022-SHOE.
“It was a great shoe department to begin with,” Stedman recalls, “and then they expanded it. Literally, you could find anything and everything you could ever imagine and ever want. And it was always packed and bustling.” In the 2008 film The Women, Annette Bening’s character offered a simpler, widely accepted verdict: “Nobody. Hates. Saks.” At the time, few within the fashion industry or consumer base would have disagreed.

Over the past few years, however, the company’s storied prestige has taken a severe beating. Deep financial and managerial problems, many directly tied to the complex 2024 acquisition of Neiman Marcus, culminated in Saks Global filing for Chapter 11 bankruptcy protection in January with a staggering $3.4 billion in debt. Following a comprehensive restructuring process, the firm announced in June that it had officially emerged from bankruptcy. Operating with a significantly reduced footprint of physical stores, the parent company has been renamed Exemplar Luxury Group. Whether the iconic nameplate can recover its former stature—and regain the affection of discerning luxury shoppers—remains an open question.
Long before the formal bankruptcy filing, the everyday shopping experience had already begun to deteriorate. Customers visiting their once-beloved locations increasingly encountered sporadic, sparse assortments in their favorite categories, signaling deeper structural distress behind the scenes.
“People just felt that it wasn’t the same Saks that they used to shop at,” says Anita Berger, a former senior salesperson at the Saks Fifth Avenue location in St. Louis, Missouri, which had cultivated fiercely loyal clientele for more than half a century.
To be fair, traditional department stores have faced mounting industry pressure for years. Modern consumers increasingly shop online through brand websites, direct-to-consumer platforms, multi-brand digital marketplaces, and resale sites like The RealReal. Instead of spending leisurely afternoons browsing physical racks and receiving personalized advice from trusted floor staff, shoppers increasingly find their inspiration through social media feeds. Furthermore, tailored suits and men’s ties no longer anchor everyday wardrobes the way they once did, a shift that accelerated significantly in the wake of the COVID-19 pandemic. The classic grand-department-store model—featuring floor after cavernous floor packed with traditional merchandise—may well be outdated.
“What you have is literally this transition and shift in the paradigm,” says Marshal Cohen, chief retail adviser at Circana, a consumer-buying pattern tracking firm. “The model needs to adjust.” As Bain & Company noted in a 2024 report examining the state of American department stores, many U.S. shoppers have grown indifferent or outright averse to the legacy format.

Even before Saks Fifth Avenue finalized its purchase of Neiman Marcus in December 2024, industry insiders and partner brands sensed trouble as familiar buyers and experienced salespeople began turning over at an unsettling rate.
“You could kind of smell that something was going on, just because everything was getting a little difficult,” says Daniel Wingate, founder and creative director of Wingate, a collection of sophisticated designer women’s apparel previously sold through trunk shows at various Saks Fifth Avenue locations. “The people in the stores were in and out and changing, unhappy. Then, the rumor started that they were trying to buy Neimans.”
That rumor proved true, and the acquisition saddled Saks Global with enough debt that the retailer eventually fell behind on payments for inventory. As cash flow tightened, many independent and major fashion houses felt they had no choice but to halt shipments entirely.
“Every one of my clients was saying, ‘God, the stores look so bad—there’s no inventory,’” explains Gary Wassner, CEO of Hilldun, a financing firm that guarantees payments for roughly 180 fashion and beauty brands carried across Saks Global stores, including Rick Owens, Golden Goose, Ulla Johnson, Isabel Marant, and Victoria Beckham. “The consumer was well aware walking into any Saks Fifth Avenue that the inventory was depleted. It was quite noticeable, particularly as the days wore on.”
“My floor looked so bad,” echoes Berger, the former St. Louis sales associate. “Customers would come in and say, ‘Are you closing? This looks like Saks Off 5th.’ There was nothing new and exciting because they couldn’t get anything—they owed money to everybody.”

Sales associates elsewhere reported similar inventory anomalies. “We never had a full size run of dresses,” recalls Babatunde Fakuade, who worked for nearly a year as a salesperson at Neiman Marcus Lenox Square in Atlanta. “We would get a size 2, a 12, an 8. It’s like, ‘Where are the other sizes?’ We didn’t get a delivery of full size runs of dresses for months at a time.”
The St. Louis store where Berger spent nearly a decade ultimately closed its doors in May, though she had already departed the previous September. “How they were treating us, how they were not paying, how the store looked—I just started to feel like, ‘I need to get out,’” she says. Fakuade similarly chose to leave Neiman Marcus to pursue a career as a retail business consultant, noting that leaving without another job secured made financial sense under the circumstances.
The company’s cash-flow issues extended far beyond the immediate fallout of the Neiman Marcus acquisition. Saks Global combined Saks Fifth Avenue, Neiman Marcus stores, Bergdorf Goodman, Horchow, and the discount banners Saks Off 5th and Last Call. However, Saks entered the consolidation deal already carrying substantial debt, much of it linked to its 2013 purchase by Hudson’s Bay Company, the historic Canadian retailer with roots dating back to 1670.
Early corporate moves raised eyebrows across the financial sector. The Fifth Avenue flagship itself was mortgaged in 2014 for roughly $1.2 billion, creating heavy recurring monthly debt service obligations. In 2016, the company acquired off-price retailer Gilt Groupe for $250 million to bolster Saks Off 5th, only to sell it a couple of years later for an undisclosed sum widely rumored to be substantially lower. Additional investments continued to add burdensome financial obligations to the cash-strapped company.
“There were a lot of prior Hudson’s Bay issues—leases and bonds—that Saks, through succession, became obligated on,” explains Lorenzo Marinuzzi, a partner at the law firm Morrison Foerster, which represents Saks Global’s unsecured creditors, including major luxury houses like Chanel and LVMH.

Hudson’s Bay’s financial baggage did little to reassure vendors who were waiting to be paid for delivered goods. As Marinuzzi notes, “When you’re telling your vendors that you don’t have money to pay them for goods they’ve sold or shipped or consigned or delivered to your stores, yet you’re paying off this Hudson’s Bay debt, it rubs people the wrong way.” Hudson’s Bay Company ultimately filed for bankruptcy and closed all of its remaining stores.
As the retail enterprise unraveled, many industry observers pointed toward Richard Baker, who served as Hudson’s Bay Company’s governor, executive chairman, and CEO, and subsequently assumed the role of executive chairman of Saks Global. Baker’s primary professional background is in real estate, and critics frequently argued that his approach to managing historic department stores prioritized property acquisitions and financial dealmaking over the delicate craft of retailing luxury garments. Baker previously acquired Lord & Taylor in 2006 using extensive debt financing, later selling its landmark Manhattan building to WeWork in 2017 and its retail operations to Le Tote in 2019 before the brick-and-mortar locations shut down permanently in 2020.
This real estate-centric philosophy was frequently reflected in corporate communications. A July 2024 press release announcing the planned Neiman Marcus purchase explicitly described the new entity as “a combination of world-class luxury retail and real-estate assets.” Upon finalizing the deal, Baker stated that the strategic vision was to “redefine the luxury shopping experience” through, among other initiatives, “a portfolio of prime real estate.”
“There’s a lot of head-scratching about the way Richard Baker handled himself and ran the company, his background—maybe it wasn’t the right background for this kind of retailer,” Marinuzzi says. “When people thought about the decisions that were being made and how the company was being operated, they didn’t really trust management, and they didn’t trust Richard Baker.”
When the transaction was originally announced, Baker told The New York Times that “when selling luxury products, you need beautiful stores and salespeople customers trust.” By the time Saks Global filed for Chapter 11 bankruptcy protection, many of those same stores featured thinly stocked sales floors and demoralized employees. Baker stepped down from Saks Global in January, shifting his public focus back to real estate ventures, while representatives for both Baker and Exemplar Luxury Group declined requests for interviews.

When the bankruptcy filing was finalized, the scale of debt owed to the world’s most prominent luxury conglomerates was staggering. Court documents filed in January showed that Saks Global owed more than $136 million to Chanel; roughly $60 million to Kering, the parent company of Gucci, Saint Laurent, and Bottega Veneta; about $30 million to Richemont, owner of Cartier, Montblanc, and Chloé; and nearly $16 million to the Estée Lauder Companies, whose portfolio includes La Mer, Jo Malone London, Le Labo, and Tom Ford.
While such global giants possess substantial financial cushions—including independent boutiques, alternative department store counters, and vast international distribution networks—smaller independent brands faced a far more perilous reality.
“As a small business, you have limited bandwidth,” says a senior executive at a critically acclaimed beauty brand formerly carried at Neiman Marcus. “Finances are not just endless.” Her brand has still not recovered the six-figure sum owed for orders shipped to the retailer, despite pursuing legal remedies. Without that revenue, the small management team had to let go of contracted freelancers, and a key manager subsequently departed for another role. The company is now actively working to rebuild its retail network with alternative partners.
Numerous sources spoke on the condition of anonymity due to sensitivity within the close-knit fashion industry, with many former staffers citing non-disclosure agreements or ongoing legal disputes over unpaid invoices.
Other independent labels detailed severe operational sacrifices required to survive the liquidity crisis. “You have to keep going,” explains an executive at another beauty label owed more than a quarter of a million dollars by Saks Global. “So you’re looking at your people, you’re looking at your programs. You might be cutting advertising or awareness programs. You may be cutting marketing plans, launches, photo shoots, company parties. It’s going to be rolled all the way across, because for small businesses to lose money like that is very serious. It seriously affects your bottom line.”

For a celebrity-adored women’s fashion brand, the fallout included canceling a planned runway show and forfeiting the financial deposit on the event space. Another senior executive at a lauded fashion label reported that missing payments compromised their ability to fund fabric production, button manufacturing, staff payroll, and external public relations agencies. The company was ultimately forced to lay off 20 percent of its workforce to navigate what the executive described as a “cash vacuum.”
“It will probably stall our business five years in terms of its growth trajectory,” he says, noting that his brand is owed several hundred thousand dollars and has received only one full payment for collections spanning 2024 and 2025, with other invoices settled at mere pennies on the dollar. He anticipates recovering only about 20 percent of the total debt.
Compounding the financial frustration was a breakdown in corporate communication. As payment delays stretched on, inquiries were frequently routed to administrative and financial support teams based in Bengaluru, India, where Saks Global had outsourced core corporate functions including finance, human resources, merchandising, analytics, and marketing.
“It felt like people who really were not connected to who we were,” the fashion executive says. “I’m like, ‘Who are we talking to?’ In one email, the brand’s name was not even spelled correctly.” Wingate similarly noted the disconnect, observing that dealing with overseas support teams felt less like genuine customer service and more like a deliberate stalling tactic for outstanding payments. While Wingate utilized a collection agency to recover a portion of his funds, he confirms that six figures in open invoices remain unpaid.
By contrast, industry sources indicate that many of the largest global luxury houses fared better during the restructuring, with some recovering at least half of their outstanding balances—and in certain cases, nearly all—largely due to their immense market leverage and consignment structures.

Firms like Hilldun successfully insulated their client brands, with CEO Gary Wassner noting that the financing firm paid out virtually all approved debt to its network of 180 designers, excepting invoices still undergoing reconciliation. However, smaller independent operators who lacked guaranteed financing faced stark choices. “We gave up,” says an executive who runs a unisex grooming brand owed over $100,000 by Neimans and Saks. “They promised to pay you if you would ship to them again, but I wasn’t taking that risk.”
Following its bankruptcy filing, Saks Global engaged in an aggressive corporate restructuring, shuttering 21 underperforming stores—including 18 Saks Fifth Avenue locations and three Neiman Marcus stores. Among the casualties were longstanding outposts in Chicago, where Saks had operated since 1929, alongside locations in Costa Mesa, Las Vegas, St. Louis, San Antonio, and McLean, Virginia. The company also closed more than 60 Saks Off 5th and Last Call discount outlets, leaving the lone international Saks location in Kazakhstan operational.
As sales floors were cleared out and deep inventory markdowns attracted bargain hunters, shoppers once again witnessed scenes of traditional luxury emporiums stripped of their signature upscale aesthetic, with social media platforms filling with videos documenting the closing stores. “Bad news travels faster than good news,” observes Circana adviser Marshal Cohen. “People love to share their war stories of shopping.”
As Exemplar Luxury Group emerged from bankruptcy following an injection of $1.75 billion in new capital, suppliers began receiving payments, and merchandise started flowing back into the retail network. By March, Exemplar announced that nearly 600 vendor brands had resumed shipping. A recent visit to the Saks Fifth Avenue flagship across from Rockefeller Center revealed a fully stocked sales floor, and Exemplar reports that sales across Bergdorf Goodman, Neiman Marcus, and Saks Fifth Avenue are outpacing figures from the same period in 2025, though specific growth percentages were not disclosed.
Nevertheless, industry experts caution that restoring long-term confidence among wary consumers and skeptical fashion houses will be a formidable undertaking.

“It’s hard to come out of that with both your brand partners and with your consumers,” notes Aaron Cheris, a partner at Bain & Company and head of its global retail practice. For everyday shoppers, he explains, a prolonged deterioration in service and selection “creates a bit of a doom loop that you really have to get out of.” The core challenge, Cheris emphasizes, is simple yet daunting: persuading both suppliers and customers that the business has truly reached a fresh starting point.
For independent designers choosing to remain cautious, Exemplar’s ongoing challenges may ultimately benefit competing department stores. “Now more than ever, every brand I know wants to be in Bloomingdale’s,” an industry insider notes. “It’s almost like Bloomingdale’s and Nordstrom will become what Barneys was in the ’80s.”
For longtime patrons, the emotional distance created during the retailer’s financial turmoil remains a hurdle. “It’s going to take a while to rebuild my trust,” Stedman says. “Going there during that funky period, there was no stock, everything was on sale—it was madness. During that time, what made Saks special was not there anymore. I’m going to take a wait-and-see approach and see what happens with them.”