Department stores are always in their element during the holidays, but this year’s winter shopping season will serve as a definitive and pivotal test for three major players in the American retail landscape.
While the vast array of merchandise packed into traditional department stores gives shoppers a unique opportunity to check a multitude of items off their gift lists in a single trip, the stakes have never been higher for certain brands. Retailers traditionally lean heavily into the festive season, deploying elaborate decorations, eye-catching window displays, and special in-store events to lure customers through their doors. According to Simon-Kucher’s 2026 Holiday Shopping Report, these multi-category retailers are poised to remain top destinations for browsing and purchasing products this year.
"People like department stores," Michael Appel, president of Appel Associates, noted in a phone interview, highlighting a sentiment that persists despite domestic headwinds. "The department store format, outside the United States, is working very well."
A number of retailers in the space have spent recent years striving to recapture the glory days of the traditional department store model, though they have met with varying degrees of success. Industry analysts frequently credit Dillard’s for its steadfast dedication to retail fundamentals, an approach that has yielded consistent, if somewhat lukewarm, financial results. In its most recent quarter, the regional department store even managed to gain valuable market share. Similarly, under the leadership of CEO Tony Spring, Macy’s has demonstrated clear, measurable signs of a turnaround, while Bloomingdale’s has continued to thrive by capturing market share from competitors. Nordstrom, which transitioned to private ownership, also appears to be performing well, though it is no longer required to report its performance publicly.
However, three prominent names—Kohl’s, J.C. Penney, and Saks Fifth Avenue—are walking a much more precarious tightrope. Industry experts say these brands have an immense amount at stake during retail’s critical "golden quarter" and are being watched under a microscope for concrete signs of stabilization.
"Kohl’s, J.C. Penney, and Saks are three very different bets, but each faces a critical test this holiday season," Glenn McMahon, a partner at MAC Advisory and Consulting, explained via email. "The issue is not simply whether consumers will spend; it is whether these retailers can convert holiday demand into enough profitable sales and cash flow to address deeper business challenges."
Kohl’s
Kohl’s has found its multiyear turnaround strategy dragging on with frustratingly little to show for the prolonged effort. Last year, the retailer’s fourth-quarter net sales fell by 4%, while comparable store sales dropped nearly 3%. This disappointing performance contributed to full-year declines of 4% in net sales and over 3% in comparable sales compared to the previous fiscal year.
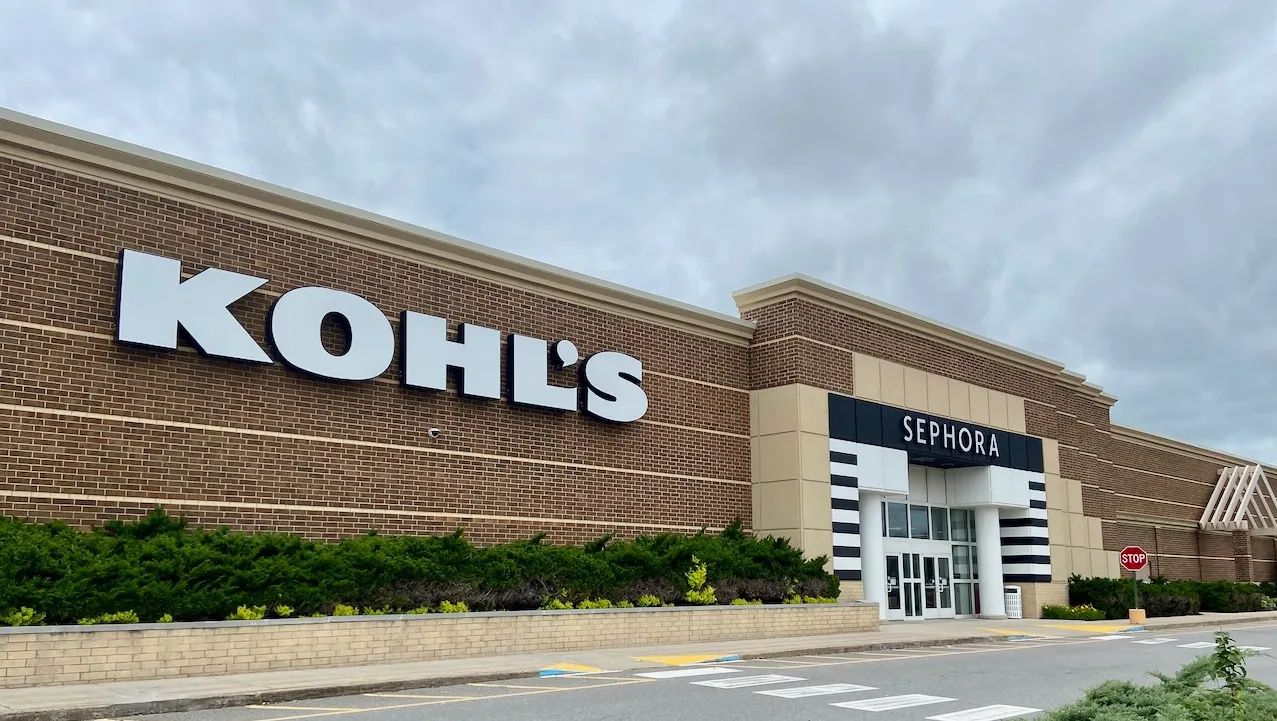
Despite these operational hurdles, the company continues to generate healthy cash flow and maintains a relatively low debt load. According to David Silverman, senior director at Fitch Ratings, this financial cushion means Kohl’s can afford to continue funding its ongoing turnaround into the coming year.
The department store welcomed a new chief merchant last month: Ryan Waymire, a former Walmart fashion executive whose extensive resume also includes stints at Wayfair, FabFitFun, Amazon, and Target. Yet, the retailer suffered a significant strategic setback this year when its high-profile Sephora shop-in-shops—long touted as a primary driver for both foot traffic and sales—suffered unexpected sales declines for two consecutive quarters.
Ongoing sales erosion poses a direct threat to the company’s ability to remain competitive in a crowded marketplace, according to McMahon. As a result, Kohl’s holiday comparable store sales, customer traffic figures, markdown levels, and gross margins will be scrutinized intensely by Wall Street and retail watchers alike.
"Kohl’s needs to give middle- and lower-income shoppers a compelling reason to choose its stores over off-price chains, mass merchants, and online rivals," McMahon said. "Another weak holiday would raise questions about how much longer Kohl’s can pursue a turnaround without further restructuring."
J.C. Penney
J.C. Penney experienced a brief glimmer of progress in 2025, but its turnaround abruptly stalled during the fourth-quarter holiday shopping period. Net sales tumbled 8% compared to the 2024 holidays, and those downward trends stubbornly continued into the following year. In its most recent quarter, the department store lost further market share, posting another 8% year-over-year decline in net sales, even though activewear and beauty products remained relative bright spots.
On the corporate side, the company benefits from its affiliation with Catalyst Brands, a retail conglomerate that houses many of the prominent names formerly operated under Authentic Brands Group and its partners. Furthermore, J.C. Penney’s co-owners, Simon Property Group and GGP (formerly Brookfield), have a powerful financial incentive to keep the retailer’s doors open. Their motivation extends far beyond retaining revenue; keeping Penney stores operational prevents the activation of co-tenancy clauses that would otherwise allow other mall tenants to exit or drastically alter their lease agreements. Simon and Brookfield originally acquired the struggling department store out of bankruptcy proceedings in 2020.
"J.C. Penney’s been on a downslide for a long time, but they’re protected, because of the fact that they need them to be in those malls," Appel observed. "They probably have to invest a lot more money in the stores. They’re treading water in my opinion."
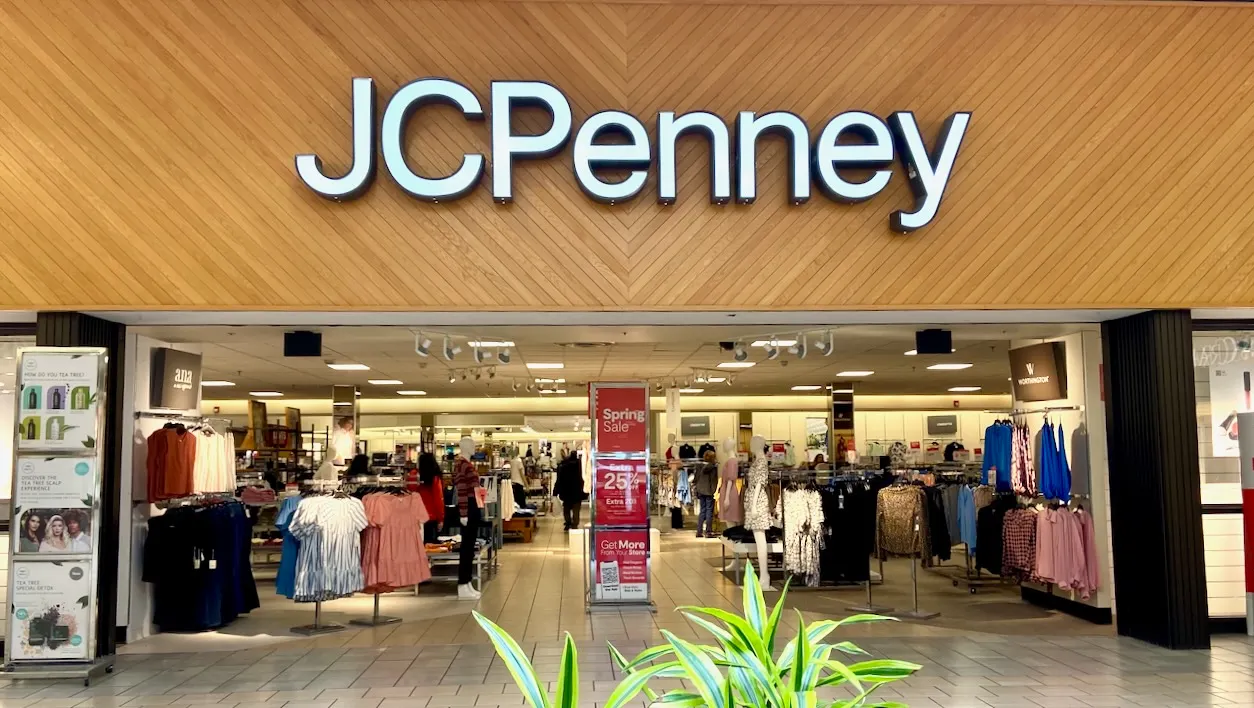
At some point, however, the retailer will be forced to demonstrate tangible operational improvements, as sustained, massive declines point directly to underlying business model risks, according to Silverman.
"Penney’s holiday performance will test whether its combination of affordability, apparel, home and beauty can drive traffic and spending without excessive discounting," McMahon said. "The risk is that persistent weak sales and thin margins leave the retailer with too little financial flexibility to invest in its future."
Saks Fifth Avenue
Following a tumultuous year marked by financial distress, Saks Global plunged into bankruptcy court early in the year—a development that felt almost inevitable to seasoned industry observers. Throughout the previous year, the company had struggled consistently to pay its vendors, resulting in severe merchandise shortages during the critical holiday shopping quarter.
Months later, the company managed to exit Chapter 11 proceedings under the banner of "Exemplar Luxury Group." Much like before, the entity operates high-end department store chains Saks Fifth Avenue, Neiman Marcus, and Bergdorf Goodman, while successfully trimming its total debt load to under $1 billion.
"Exemplar [Saks and Neiman Marcus] has the most to prove, following a year in which the company completed a bankruptcy process, changed management teams, and has implemented efforts to improve vendor relationships," Silverman noted. "The industry will be focused on the company’s inventory position and ability to re-engage with customers that have defected in recent years."
During the court-supervised restructuring process, the physical footprint of the flagship Saks banner shrank dramatically. Its full-line store count was cut in half, leaving the company with just 15 full-line locations and a minimal off-price operation dedicated strictly to selling excess inventory.
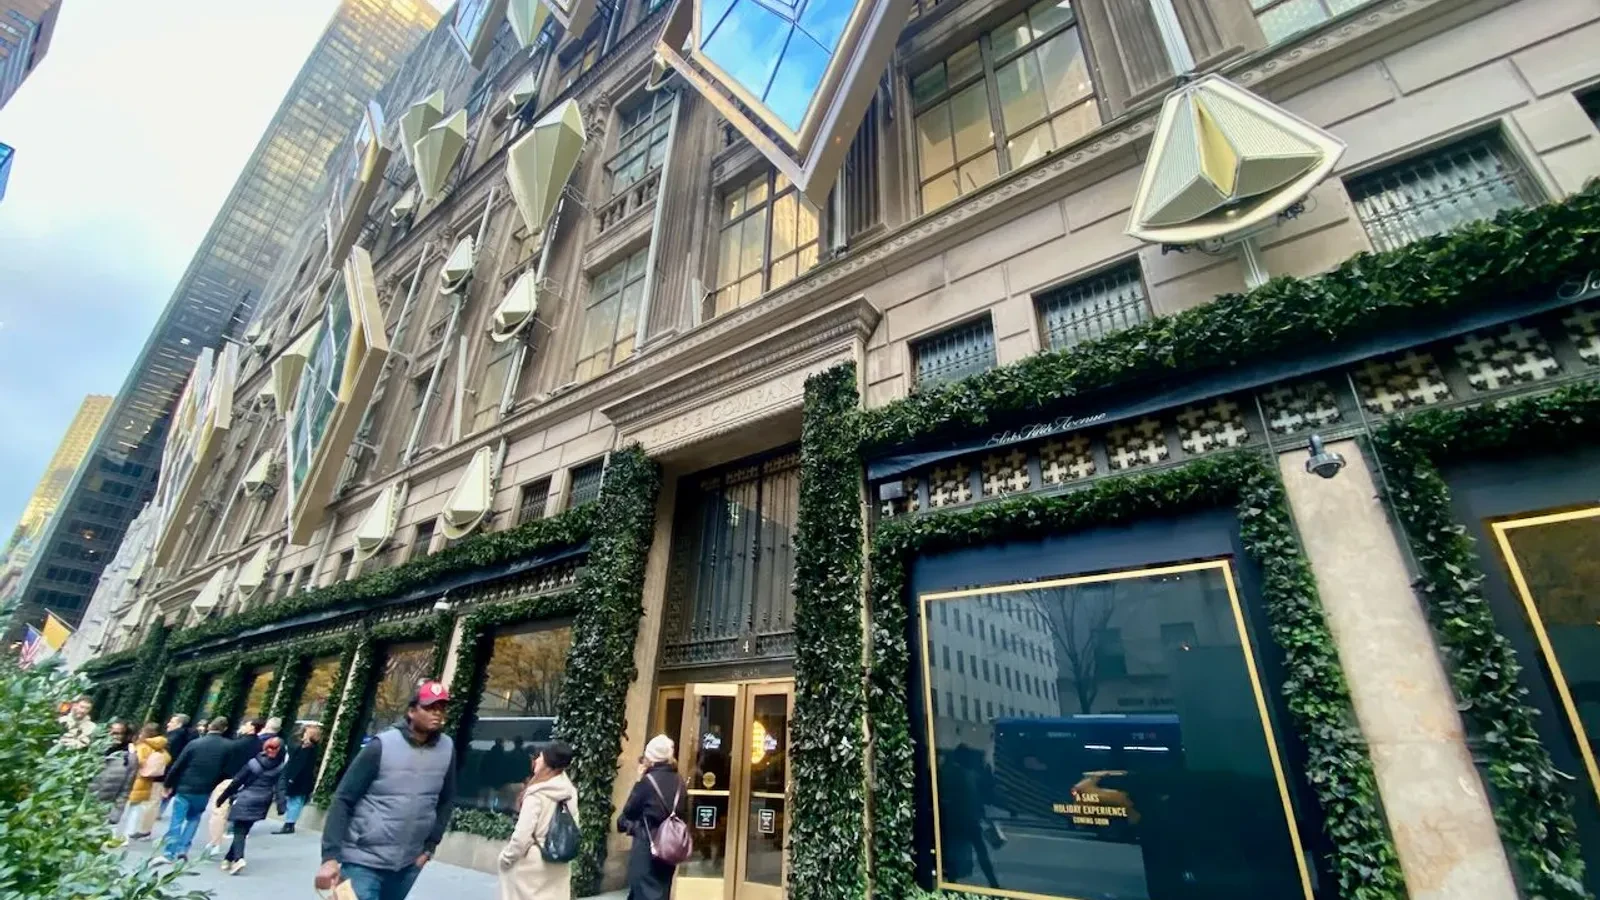
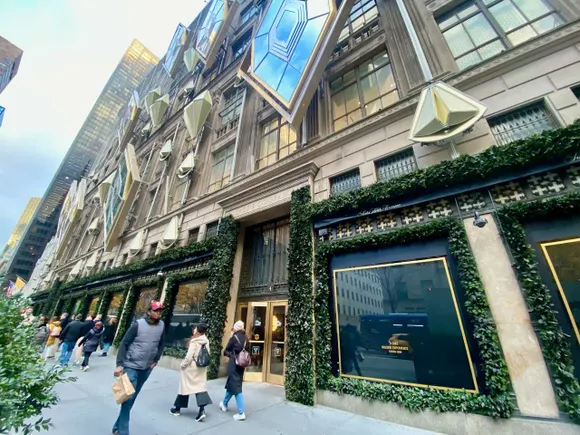
Even with a vastly reduced store fleet, analysts question whether the remaining locations are receiving adequate corporate attention. Appel pointed out that the company’s holiday marketing campaigns this year appear heavily concentrated on its iconic Manhattan flagship.
"What about the other stores? If they’re not supporting them equally—and we don’t know the answer—then they’re not going to perform well," Appel warned. "And you know what’s going to happen? They’re going to close those stores, and it’s all going to end up being Neiman Marcus. Because they don’t have scale, and they’re using the same buying team for both, which is completely ridiculous."
This structural shift is starkly illustrated by the closure of Saks’ historic store on Michigan Avenue in Chicago. For decades, the location sat directly across the street from Neiman Marcus, with both luxury department stores thriving side by side.
"It’s crazy not to have a major store on Michigan Avenue," Appel said. "They might think that by closing Saks, maybe they’ll get a lot of customers going to Neiman’s, but they’re different customers. So I think that’s baloney. They don’t want to make the investment. They’re not taking the long term view."
Other market observers see Exemplar as a whole facing an uphill battle this season. Most high-end retailers have struggled over the past year as aspirational luxury shoppers have noticeably pulled back and redirected their spending. Navigating this consumer shift is exceptionally complex. At Exemplar, high-end demand, full-price selling strategies, inventory management, vendor relations, and cash generation will all face intense external scrutiny, according to McMahon. Appel predicts that Saks, in particular, will continue to hemorrhage market share to competitors like Nordstrom and Bloomingdale’s.
"Strong holiday sales would help, but sales alone will not resolve the larger question: can Saks generate sufficient cash to support its financial obligations and make the combined business work?" McMahon concluded. "A weak season could intensify pressure on an already complicated turnaround."